Milan, Italy: For years, Milan was the understudy in Europe's data centre story. By 2028, it could be a headline act. New research from CBRE forecasts that 255MW of new data centre capacity will be delivered in the city across 2027 and 2028, with the vast majority designed to support hyperscale and neocloud deployments.
If that pipeline is realised, Milan will leapfrog Dublin to become Europe's fifth-largest data centre market. The gap is already slim: at the end of Q3 2026, just 100MW of operational capacity separated the two cities. Italy's colocation market has expanded sixfold since 2020, fuelled by international operators building large-scale facilities for hyperscaler demand.
Dublin, meanwhile, shows what happens when the power runs out. Since a de facto moratorium on new grid connections was declared in late 2021, the growth rate of supply there has declined in four of the five years. Milan's rise is the mirror image, driven by hyperscalers expanding cloud regions and accelerating AI initiatives across Europe. Much of the activity is concentrated west of the city, with major projects also under way in Siziano and the wider metropolitan area. Yet growth continues despite mounting power constraints in parts of the region, where connection lead times are lengthening as demand intensifies.
Andrew Jay, Head of Data Centre Solutions, Europe at CBRE, said: "Milan's accelerated development trajectory highlights the city's transition from a secondary market into a top European data centre hub. This evolution reflects a broader geographic diversification of data centre activity, with Southern Europe growing in relevance when compared to traditional data centre clusters, namely Frankfurt, London, Amsterdam, Paris and Dublin (FLAPD)."
Kevin Restivo, Head of Data Centre Research, Europe at CBRE, added: "The market offers compelling growth prospects alongside improving fundamentals and greater institutional interest. However, the pace of expansion necessitates careful monitoring, particularly in relation to absorption rates and pre-leasing activity, to ensure supply remains aligned with demand over the medium term."
The research leaves a question that matters most to investors and developers: how much of the 255MW has actually secured a grid connection? With lead times lengthening, secured power, rather than land or shell capacity, may be the scarce asset that separates deliverable projects from stranded ones. Dublin's experience suggests that a market can be capped by its grid long before demand fades, and anyone underwriting Milan's pipeline will want to know where the queue sits, which projects are pre-let, and how much of the supply is truly firm.
People mentioned
- Andrew Jay: Head of Data Centre Solutions, Europe, CBRE
- Kevin Restivo: Head of Data Centre Research, Europe, CBRE
Companies mentioned
- CBRE Group, Inc.: Global commercial real estate services and investment firm headquartered in Dallas (NYSE: CBRE); publisher of the research on Milan's data centre market
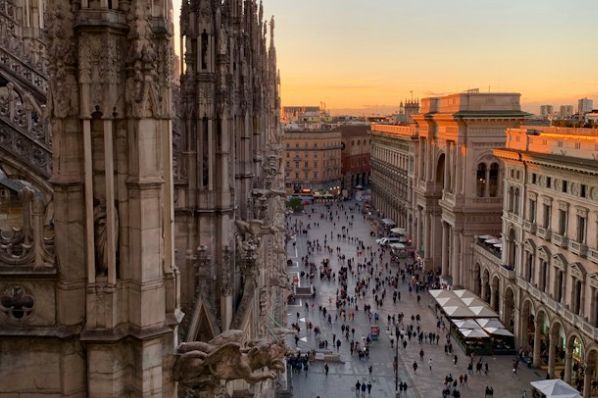
Image Source: Photo by Yakov Manshin on Unsplash
Get the latest commercial real estate news, investment insights, and property trends from Europe Real Estate, trusted by professionals since 1999.
Sign up for free weekly updates. Join here