Dublin, Ireland: Activity in Dublin's industrial and logistics property market reached its highest quarterly level in almost three years during Q3 2026, according to new research from Savills Ireland. A total of 76,570m² of space was taken up across 17 transactions during the quarter, representing a 65% increase on the same period last year and the strongest quarterly performance since Q4 2023. Total take-up for the first nine months of 2026 now stands at approximately 176,500m², putting the market firmly on course to exceed last year's annual total.
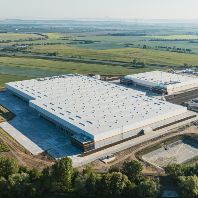
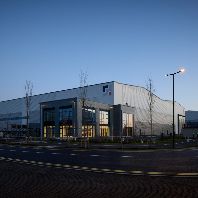
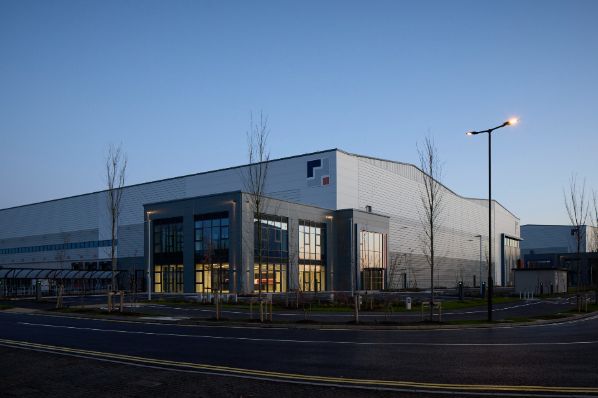
Demand was heavily skewed towards larger facilities, with four transactions exceeding 9,290m² each and the average deal size rising to approximately 4,505m², its highest level since late 2023. The south-west Dublin suburbs dominated, accounting for 84% of all space taken during the quarter, well above the five-year average of 52%. All five of the quarter's largest transactions were concentrated in this submarket, including two lettings at Mountpark Grange Castle West, where more than 41,800m² of speculatively developed space completed last year has now been fully let. The consequence has been swift and stark: vacancy in the south-west fell from 3.1% in Q2 to just 1.5% in Q3.
"The third quarter has been particularly strong for Dublin's industrial and logistics market, with a clear return of larger transactions. Four deals exceeding 100,000 sq ft in a single quarter is a significant level of activity and demonstrates that occupiers are continuing to commit to substantial facilities. South-west Dublin remains the standout location. The fact that more than 450,000 sq ft of speculative space at Mountpark Grange Castle West has now been fully let shows the depth of demand for well-located logistics accommodation. While we have seen new supply coming through, availability remains extremely limited in certain locations. With vacancy in the south-west now at just 1.5%, occupiers looking for larger facilities have relatively few options, particularly where they have specific operational or location requirements," said Jarlath Lynn, Director, Industrial and Logistics at Savills Ireland.
Third-party logistics operators led occupier demand, accounting for 48% of total take-up, followed by industrial occupiers at 23% and first-party logistics operators at 21%. Notably, AI-related infrastructure and data centre activity is increasingly underpinning demand for associated industrial accommodation as investment in artificial intelligence continues to accelerate. Almost half of all space transacted during the quarter, at 49%, was in buildings completed since 2020, underscoring occupiers' preference for best-in-class, modern facilities. Prime rents rose by €0.25 per sq ft during Q3 to reach €158.77 per m² (€14.75 per sq ft), marking the sixth consecutive quarter of prime rental growth and an increase of €10.76 per m² over the past 12 months. Secondary rents also moved upward to €126.56 per m². The overall Dublin vacancy rate edged down from 2.8% to 2.6%, leaving the Irish capital among the tightest industrial and logistics markets in Europe.
For investors and developers, the supply pipeline is the critical variable to watch. A total of 37,630m² of new accommodation was completed in Q3 across seven units, with 89% of that volume delivered in Dublin's north suburbs. A further 18,560m² is scheduled for completion in Q4, bringing anticipated 2026 deliveries to just over 92,900m², below the five-year annual average of approximately 130,060m². Development activity is expected to increase in 2027, with around 130,060m² scheduled for completion. However, with land constrained, construction costs elevated and the south-west submarket already at 1.5% vacancy, the arithmetic for developers willing to move now is compelling: rental growth has been uninterrupted for six quarters, speculative space continues to let rapidly, and the window to deliver product ahead of anticipated demand in 2027 and 2028 is narrowing.
Jarlath Lynn added: "We expect occupier demand to remain healthy, particularly for modern, efficient buildings in established logistics locations. However, the limited availability of suitable sites, combined with higher construction costs, will continue to influence both development decisions and rental levels."
Get the latest commercial real estate news, investment insights, and property trends from Europe Real Estate, trusted by professionals since 1999.
Sign up for free weekly updates. Join here
People and companies mentioned
-
Jarlath Lynn, Director, Industrial and Logistics, Savills Ireland
-
Savills Ireland, property advisor and author of the Q3 2026 Dublin Industrial and Logistics Market report
-
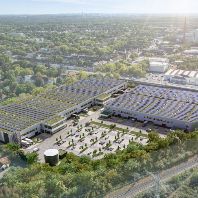
Mountpark Grange Castle West, logistics park in south-west Dublin; more than 41,800m² of speculatively developed space now fully let
Image Source: Mountpark Grange Castle West